Leaving the Scene Of A Car Accident: What Happens to Your Car Insurance?

Introduction

Leaving the scene of a car accident.

A minor bump can happen in seconds, but leaving the scene of a car accident can create much bigger problems.

UK drivers may have legal duties to stop, exchange details and, in some circumstances, report the accident to the police.

Then there’s your car insurance to think about.

A collision, claim or motoring conviction could affect what you pay for cover later, so knowing what to do before panic takes over matters.

Leaving The Scene Of A Car Accident: What Does It Actually Mean?

Most people hear “leaving the scene” and imagine a dramatic hit-and-run.

But it doesn’t have to look like that.

A low-speed collision can still create legal responsibilities.

Even a seemingly insignificant knock may involve another vehicle, property, an animal or an injured person.

Here’s the important part.

Section 170 of the Road Traffic Act 1988 sets out when drivers must stop following certain road accidents.

Simply deciding that “there wasn’t much damage” isn’t always enough.

When Are You Legally Required to Stop?

If you’re involved in a qualifying accident, you must stop.

That can include accidents causing injury to another person or damage to another vehicle or certain property.

So, yes, that little scrape can matter.

The safest approach is simple: stop somewhere safe and establish what has happened.

Don’t drive away because the damage looks trivial from behind the wheel.

What appears to be a tiny mark could look very different once both cars are inspected.

And there’s another reason to stop.

Modern cars are packed with cameras, doorbell footage and dashcams.

Driving away doesn’t mean nobody saw what happened.

Quick takeaway: If you’re involved in an accident, don’t assume “minor” means “nothing to deal with”.

What Information Should You Give?

Stopping is only part of the process.

Where required, you should be ready to provide your name and address.

You may also need to provide the vehicle owner’s details and registration number.

If someone has been injured, insurance details can also become particularly important.

In other words:

Don’t make the roadside conversation harder than it needs to be.

Take photographs, record the other vehicle’s registration and carefully note the details you’ve exchanged.

Avoid arguing about who was at fault.

That can be dealt with later.

Your immediate job is to stay safe, gather information and meet your legal obligations.

What Happens If You Are Leaving The Scene Of A Car Accident?

This is where a small accident can become a much bigger headache.

Failing to stop when legally required can amount to an offence.

Failing to report an accident when required can also amount to an offence.

And those aren’t necessarily the same thing.

There’s the catch.

A driver might stop briefly but still fail to provide the required information.

Another driver might leave without exchanging details but subsequently report the accident correctly.

The exact circumstances matter.

That’s why “I stopped for a minute” doesn’t automatically answer the question.

Leaving The Scene Of A Car Accident: Failing To Stop vs Failing To Report

These phrases often get bundled together.

However, they’re worth separating.

Failing to stop concerns your obligation to stop following a qualifying accident.

Failing to report concerns circumstances where the accident must then be reported to the police.

If the required details aren’t exchanged at the scene, Section 170 can require the accident to be reported as soon as reasonably practicable.

Where that reporting duty applies, the legislation sets an outside limit of 24 hours.

But don’t treat 24 hours as a target.

“As soon as reasonably practicable” is the important wording.

If you realise you’ve made a mistake, acting promptly makes far more sense than watching the clock.

Do You Have To Report Every Car Accident To The Police?

No.

This is where plenty of confusion starts.

An accident doesn’t automatically require a police report simply because two cars touched.

Where the necessary details have been exchanged, there may be no separate duty to report that collision to police.

However, the circumstances can change that.

For example:

If you cannot provide the required details, reporting obligations may arise.

In accidents involving injury, there are also specific requirements concerning insurance information.

The Highway Code gives drivers practical guidance on what to do following a collision.

And remember:

Reporting something to the police and notifying your car insurer are two different issues.

Your insurance policy may require you to tell your insurer about an accident even when you don’t intend to claim.

We’ll come back to that.

What If You Didn’t Realise You Had Hit Something?

This is more plausible than it sounds.

Picture a cramped supermarket car park.

You reverse slowly, hear nothing unusual and drive home.

Later, somebody contacts you about damage to their parked car.

Now what?

Whether a driver genuinely knew an accident had happened can become highly relevant to the individual circumstances.

But don’t invent a story because it feels convenient.

If you’ve discovered that an accident may have happened, deal with the situation promptly.

Contact the appropriate people, preserve any dashcam footage and write down what you remember while it’s fresh.

Small details disappear surprisingly quickly.

What If You Panicked and Drove Away?

People don’t always behave logically after a collision.

Adrenaline kicks in.

Your thoughts race.

And sometimes somebody makes the wrong decision.

But panic doesn’t make the problem disappear.

If you’ve driven away and then realise you should have stopped or reported the accident, don’t simply hope nothing happens.

Take action.

Depending on the circumstances, that may mean contacting the police promptly and notifying your insurer.

And this brings us to the part many drivers worry about most:

What will all of this do to the price of your car insurance?

Does Leaving The Scene Of A Car Accident Affect Your Car Insurance?

Potentially, yes.

An accident may affect your car insurance, particularly if it leads to a claim or motoring conviction.

Here’s the key point.

Insurers don’t all price risk in the same way.

One company may increase your premium sharply, while another may still offer competitive cover.

That’s why comparing car insurance options matters after an accident.

Do You Still Need to Tell Your Insurer?

Possibly.

Making a claim and notifying your insurer are not always the same thing.

Your policy may require you to report an accident even if you plan to pay for repairs yourself.

So don’t guess.

Check your policy wording and provide accurate information.

Trying to hide an accident simply to keep your premium down could cause bigger problems later.

Will Your Car Insurance Become More Expensive?

It can.

However, there’s no fixed amount by which your premium will increase.

Your insurer considers numerous factors, including your claims history, vehicle, postcode, age and driving record.

And here’s where shopping around becomes important.

Your renewal quote isn’t automatically the best price available.

Even after an accident, another insurer may offer significantly cheaper cover.

Our guide to very cheap car insurance explains other ways to reduce the price you pay.

Can You Still Find Cheap Car Insurance After An Accident?

Yes, potentially.

An accident doesn’t automatically prevent you from finding cheap car insurance.

But you need to compare properly.

Don’t make this mistake.

If your existing insurer sends a much higher renewal price, don’t simply accept it because switching feels complicated.

Compare quotes first.

You can also use our five ways to save money on car insurance before buying your next policy.

And always compare like-for-like cover.

The cheapest quote isn’t much use if the policy leaves out something important.

What Should You Do After A Car Accident?

Keep things simple.

  1. Stop safely.
  2. Check whether anyone is injured.
  3. Exchange the required details.
  4. Take photographs.
  5. Record witness information.
  6. Contact the police where required.
  7. Notify your insurer where necessary.

One more thing.

Avoid arguing about fault at the roadside.

Gather the facts first.

What If The Other Driver Is Leaving The Scene Of A Car Accident?

Try to record their registration number immediately.

Take photographs and look for witnesses, CCTV or dashcam footage.

Then report the incident where appropriate and contact your insurer.

Evidence matters.

Even a nearby doorbell camera could help establish what happened.

Could Leaving The Scene Of A Car Accident Affect Future Insurance Quotes?

Yes.

Claims, convictions and driving history can influence future premiums.

If an insurer asks about them, answer accurately.

But don’t assume expensive insurance is inevitable.

Different insurers assess the same driver differently.

Comparing providers remains one of the simplest ways to look for the cheapest car insurance available for your circumstances.

If you’re considering moving insurers, our guide to switching car insurance explains what to check first.

Conclusion

Don’t make a small accident bigger.

Accidents happen.

What you do afterwards matters.

Stop, exchange the required details and report the incident when necessary.

If you’ve already driven away, deal with the situation promptly rather than ignoring it.

Then check your insurance.

An accident may increase your premium, but your existing insurer doesn’t automatically offer the cheapest price.

Compare your options, provide accurate information and look for suitable cover at the lowest sensible cost.

That’s ultimately what Cheap Car Insurance should mean.

Similar Car Insurance Guides

You may also find our guides to comprehensive vs third-party insurance, telematics car insurance and the cheapest cars to insure useful.
 

Airbag Deployed In A Car Accident? What UK Drivers Should Do Next

Introduction

Airbag accident….

An airbag going off can leave you sore, shaken and unsure what to do next, especially when you also need to think about your Car Insurance.

In this guide, we’ll cover:

  • What to do immediately after an airbag deploys.
  • When airbag injuries may need medical attention.
  • What details to collect after an accident.
  • When to contact the police.
  • How an accident may affect your insurance.
  • How to look for Cheap Car Insurance afterwards.

What Do You Have To Do If Airbags Touch You In An Accident?

Airbags deploy extremely quickly.

So, although they help protect you, they can still leave bruises, redness, grazes or soreness.

First things first.

Check yourself and your passengers for injuries.

If anyone is seriously injured, struggling to breathe or unconscious, call 999.

Then focus on making the situation safe.

Don’t worry about repair costs or the cheapest car insurance while you’re still dealing with the accident.

People come first.

Safety first. Insurance second.

If you can leave the vehicle safely, move away from traffic and find somewhere secure.

However, don’t put yourself at greater risk simply to get out of the car.

Why Does An Airbag Accident Hurt When It Goes Off?

An airbag isn’t a soft cushion that gently appears in front of you.

It has to inflate in a fraction of a second.

That force can leave marks on your face, arms, hands or chest.

Your seat belt may also cause soreness during the same impact.

Here’s the important bit.

Don’t assume every ache came from the airbag.

The collision itself can cause injuries too.

If pain is severe, worsening or worrying, seek medical help.

Can An Airbag Accident Burn You?

Yes.

Airbag deployment can sometimes leave burns, abrasions or irritated skin.

If you suffer a burn, NHS guidance recommends cooling it with cool running water for at least 20 minutes.

Avoid using ice or iced water.

And don’t improvise.

If the burn looks serious, covers a large area or causes significant pain, seek medical advice.

Your health matters more than documenting every detail for an insurance claim.

When Should You Get Medical Help?

Some airbag injuries are minor.

Others need proper assessment.

Call 999 if someone has serious injuries, loses consciousness or has difficulty breathing.

For less urgent concerns, NHS 111 can advise you on what to do next.

There’s another point worth remembering.

Adrenaline can mask pain immediately after a crash.

So don’t ignore symptoms simply because you initially felt fine.

What Should You Do Immediately After An Airbag Accident?

Once everyone is safe, start dealing with the practical side.

That includes collecting information for your insurer.

1. Stop And Make The Scene Safe

If you’re involved in an accident, stop.

Use your hazard lights where appropriate and stay aware of passing traffic.

The Highway Code advises drivers to avoid creating further danger after an incident.

In short:

Don’t turn one accident into two.

2. Check Everyone For Injuries

Check yourself first.

Then check passengers and other people involved where it is safe to do so.

If someone needs urgent help, call 999.

At this stage, whether you have comprehensive cover or another car insurance option can wait.

3. Exchange Details

If the accident causes injury or damage, you may need to provide your name, address and vehicle registration.

If you don’t own the vehicle, the owner’s details may also be required.

Don’t rely on memory.

Record:

  • Names and contact details.
  • Registration numbers.
  • Vehicle details.
  • Insurance information.
  • Witness details.
  • The time and location.

Stick to the facts.

Avoid arguing about blame at the roadside.

4. Take Photos

If it is safe, photograph the vehicles and damage.

Also capture number plates, road markings, signs and the surrounding area.

Photographs can help later when you explain what happened to your Car Insurance provider.

But safety still comes first.

Never stand in moving traffic just to get a better picture.

5. Report The Accident When Required

Not every accident requires police attendance.

However, GOV.UK states that if you don’t provide the required details at the scene, you must report the accident to police within 24 hours.

That deadline matters.

Once the immediate situation is under control, you can start thinking about the claim itself.

And that’s where the insurance questions begin.

Do You Have To Tell Your Car Insurance Company?

In most cases, yes.

Even if you don’t plan to claim, your policy may require you to report the accident.

That distinction matters.

Reporting an accident and making a claim are not always the same thing.

Check your policy wording and contact your insurer as soon as reasonably possible.

Delaying could cause problems later.

And if you’re unsure what can affect cover, read our guide to what can invalidate your car insurance.

Petrol Money Lift Legality: Why That Lift Could Invalidate Your Car Insurance

Does An Airbag Going Off Mean Your Car Is Written Off?

No.

A deployed airbag does not automatically mean your car will be written off.

However, repairs can become expensive.

Airbags are only one part of the equation.

Insurers may also consider:

  • Structural damage.
  • Vehicle value.
  • Dashboard damage.
  • Seat belt systems.
  • Labour costs.
  • Replacement parts.
  • The number of airbags deployed.

Here’s the catch.

A relatively low-value car may become uneconomical to repair much sooner than an expensive vehicle.

So the final decision usually comes down to repair costs versus the value of the car.

Will An Airbay Accident Increase Your Car Insurance?

Possibly.

But there isn’t a fixed percentage increase that applies to everyone.

Insurers assess risk differently.

Your future premium may depend on your claims history, circumstances of the crash, vehicle, location and other rating factors.

Even a non-fault accident may still need to be declared when an insurer asks about previous incidents.

And this is where shopping around matters.

One insurer might increase your renewal sharply.

Another may price the same driver very differently.

That’s why accepting your renewal automatically can be expensive.

If your premium rises, compare alternatives before paying.

You can also look at our five ways to save money on car insurance.

Can You Still Get Cheap Car Insurance After An Airbag Accident?

Yes.

Having an accident doesn’t mean you’re permanently locked out of Cheap Car Insurance.

However, you may need to compare more carefully.

Insurers use different pricing models, so quotes can vary significantly.

The key point?

Don’t assume your current insurer will remain the cheapest.

Compare the total policy, not just the headline price.

Look at the excess, cover level, optional extras and any restrictions.

If your renewal has jumped, it may also be worth considering whether you should switch car insurance.

Finding very cheap car insurance is useful.

But only if the policy still gives you the cover you actually need.

Can You Drive After The Airbags Have Deployed?

Just because the engine starts doesn’t mean the car is safe to drive.

Airbag deployment usually means the vehicle has experienced a significant impact.

Other safety systems may also have been affected.

So don’t guess.

If you have doubts about the condition of the vehicle, arrange recovery and proper inspection.

Driving a damaged car could create another risk.

And that is the last thing you need.

Common Mistakes To Avoid After An Airbag Accident

A stressful accident makes simple mistakes surprisingly easy.

Try to avoid these:

  • Leaving without exchanging details.
  • Forgetting to take photographs.
  • Arguing about blame at the roadside.
  • Ignoring worsening pain.
  • Delaying contact with your insurer.
  • Assuming deployed airbags mean an automatic write-off.
  • Driving a damaged car without checking it is safe.
  • Accepting an expensive renewal without comparing alternatives.

One final warning.

Don’t give inaccurate information to your insurer because you think it might keep your premium down.

Accuracy matters.

Answer questions truthfully and provide the information your insurer requests.

How To Find Cheaper Car Insurance After An Airbag Accident

If your next renewal increases, there are still ways to control costs.

Start by comparing quotes.

Then check whether your annual mileage is still accurate.

Consider your voluntary excess carefully.

And make sure you’re comparing equivalent levels of cover.

You can also review comprehensive versus third-party insurance before deciding purely on price.

Sometimes comprehensive insurance can be competitively priced.

So never assume less cover automatically means Cheap Insurance UK drivers will pay less.

Finally, consider the car itself.

Insurance costs can vary enormously between models.

If you’re replacing a written-off vehicle, our guide to the cheapest cars to insure can help you narrow the options.

Conclusion

An airbag going off can be frightening, but the order of priorities is simple.

People first.

Evidence second.

Insurance next.

Check for injuries, make the scene safe, exchange details and record what happened.

Then contact your insurer and deal with the claim.

And if the accident pushes your premium up, don’t assume you have to accept it.

Comparing providers could still help you find the cheapest car insurance available for your circumstances.

Similar Guides

If you found this useful, you may also want to read our guides to courtesy car insurance, breakdown cover and how insurers calculate car insurance.

Bogus Car Insurance Claims Are Rising: What UK Drivers Need to Know

Introduction

A bogus car insurance claim can become a serious problem for UK motorists, especially when an innocent driver gets pulled into a dispute they never expected.

A fraudulent claim might involve an invented accident, exaggerated injuries, inflated repairs or passengers who were never there.

Here’s the problem.

Fraud doesn’t just cost insurance companies money.

Those extra costs can add pressure to the wider insurance market and, ultimately, motorists’ premiums.

So, what should you watch for?

And there’s another issue.

You don’t necessarily need to do anything wrong to become involved.

Someone else can exaggerate an accident, invent passengers or deliberately create a collision.

That’s why understanding how these claims work matters.

Why Bogus Car Insurance Claims Matter

Insurance fraud has existed for decades.

However, motor insurance remains an obvious target because claims can involve vehicles, injuries, repairs and several people.

Some fraud is carefully planned.

Other cases begin with a genuine accident before somebody decides to exaggerate what happened.

Here’s why that matters.

Insurers still have to investigate.

That costs money.

And those costs form part of the wider insurance market.

Of course, fraud isn’t the only factor affecting your premium.

Repair costs, theft levels, your postcode, your car and your driving history can all influence what you pay.

But it doesn’t stop there.

Fraud adds another unwanted cost.

So honest motorists can end up feeling the consequences.

That makes comparing Cheap Car Insurance particularly important when renewal time comes around.

Your current insurer might still offer the best deal.

But assuming it will could prove expensive.

What Are Bogus Car Insurance Claims?

A bogus car insurance claim involves deliberate dishonesty.

However, that doesn’t always mean the accident itself was fake.

Sometimes the crash genuinely happened.

The dishonesty comes afterwards.

This is where things get interesting.

Someone might exaggerate an injury.

They could claim for damage that existed before the collision.

Or they might inflate repair costs.

Then there are more organised scams.

These can involve deliberately creating accidents purely to generate insurance claims.

They’re often described as “crash for cash” schemes.

Now for the worrying bit.

An innocent motorist can unknowingly become part of the fraud.

The driver may believe they simply caused an unfortunate collision.

In reality, somebody may have engineered it.

Common Types Of Fraudulent Car Insurance Claims

Bogus claims come in several forms.

Some are sophisticated.

Others are surprisingly simple.

Staged accidents

A staged accident happens when somebody deliberately causes or engineers a collision.

They may brake suddenly or manipulate another driver into hitting them.

The aim is usually simple.

Create an accident.

Then make a claim.

But there’s a catch.

The innocent driver may believe they caused the crash.

That can make the scam difficult to spot immediately.

Some fraudsters may also use other vehicles or passengers to make the incident appear more convincing.

So what looks like a straightforward accident can become much more complicated later.

Exaggerated injury claims

Not every dishonest claim involves a fake collision.

Sometimes the accident is completely genuine.

However, somebody may exaggerate the consequences afterwards.

They might claim their injuries were far worse than they actually were.

Or they could exaggerate how long those injuries affected them.

The key point?

A genuine injury claim and a deliberately inflated claim are not the same thing.

Most people making legitimate claims simply want fair compensation.

The problem begins when somebody knowingly misrepresents what happened.

Inflated vehicle damage

Vehicle damage can also be exaggerated.

A crash may genuinely damage a bumper or panel.

However, somebody could then attempt to add older, unrelated damage to the claim.

This is where evidence matters.

Take photographs of both vehicles after an accident whenever it’s safe.

Capture the registration plates too.

Photograph the road, surrounding area and vehicle positions.

Those images could become extremely useful if the story changes later.

Drivers should also understand exactly what their own policy covers.

Our guide to car insurance options explains the main types of cover available.

Phantom passengers

This type of claim can be especially frustrating.

Imagine colliding with a car containing one person.

Later, several people apparently claim they were passengers.

Those additional passengers may then allege injuries.

And suddenly, one claim becomes several.

If possible, note how many people were inside the other vehicle.

Better still, write it down with the rest of the accident details.

Small observations can become surprisingly important later.

Completely fabricated claims

At the extreme end, the alleged accident may never have happened at all.

Someone could attempt to build a claim around an invented collision or event.

It sounds audacious.

Yet fraudulent claims don’t need to remain convincing forever.

They only need to look believable enough initially to start the process.

So, what happens next?

Insurers can compare evidence, driver statements, vehicle damage and claim histories.

If something doesn’t add up, the claim may receive closer scrutiny.

Can Someone Make A False Bogus Car Insurance Claim Against You?

Yes.

Someone can allege that you caused an accident even when you completely dispute their version.

However, there is an important distinction.

Making a claim isn’t the same as proving one.

Your insurer can investigate what happened.

They may consider photographs, witness statements, dashcam footage, vehicle damage and both drivers’ accounts.

So, what does that mean for you?

Don’t automatically assume a dishonest allegation will succeed.

Evidence matters.

A dashcam can be particularly useful because it records events independently.

Photographs can help too.

So can witnesses.

Our separate guide explains what happens if someone makes a false car insurance claim against you.

And here’s the important part.

If somebody makes a bogus claim against you, what you do next can make a big difference.

What Should You Do If Someone Makes A Bogus Car Insurance Claim Against You?

First, contact your insurer as soon as possible.

Explain clearly why you believe the claim is false or exaggerated.

Now comes the important part.

Gather everything that could support your version of events.

That might include photographs, dashcam footage, witness details, messages, CCTV or a police reference number.

Write down what happened while you still remember the details.

Include the time, location, weather, vehicle positions and number of people involved.

Small details can make a big difference.

If possible, avoid arguing directly with the other driver.

Instead, give your insurer the evidence and allow them to investigate.

You should also keep copies of any correspondence you receive.

That creates a clear record if the dispute continues.

How Do Insurers Investigate Suspicious Claims?

Insurers don’t have to accept every claim at face value.

They can compare what each person says against the available evidence.

So, what are they looking for?

They may examine photographs, vehicle damage, witness statements and dashcam footage.

They can also look for inconsistencies between different versions of the accident.

Sometimes, the physical damage itself raises questions.

For example, the alleged collision may not match the location or severity of the damage claimed.

And that’s where stories can start to unravel.

Insurers may also examine previous claims where something appears unusual.

However, every case is different.

A disputed claim doesn’t automatically mean fraud has taken place.

Why Dashcams Can Be So Useful

A dashcam won’t prevent every false claim.

However, it can provide an independent record of what actually happened.

Think about it.

Two drivers can remember the same collision very differently.

A camera doesn’t have that problem.

Footage may show who changed lanes, who stopped suddenly or what happened at a junction.

Rear-facing footage can also provide valuable context.

So, if you already use a dashcam, make sure it works properly.

And after an accident, save the footage quickly before the device overwrites it.

Could Bogus Claims Make Car Insurance More Expensive?

Potentially, yes.

Insurance companies price policies around risk and the cost of claims.

Fraud adds unnecessary costs to that system.

But here’s the catch.

Your own premium depends on far more than fraud alone.

Your age, postcode, vehicle, occupation, driving record and annual mileage can all influence the price.

That’s why two apparently similar drivers can receive very different quotes.

And it’s also why shopping around matters.

If your renewal jumps unexpectedly, don’t automatically accept it.

Compare alternative policies and check what you’re actually getting for the money.

Our guide to 5 ways to save money on car insurance covers several practical ways to reduce costs.

You can also read our guide on switching car insurance before changing providers.

How Can You Protect Yourself Against False Claims?

You can’t control what another driver does.

However, you can make yourself much harder to target.

Here’s what helps.

Take photographs after every accident where it’s safe to do so.

Record the number of people inside the other vehicle.

Get witness details whenever possible.

Save dashcam footage immediately.

Write down exactly what happened.

And tell your insurer promptly.

There’s one more thing.

Make sure the information on your own policy is accurate.

Incorrect mileage, undeclared modifications or the wrong usage details can create separate problems.

If you’re looking for very cheap car insurance, price still matters.

But cheap cover only works if the policy actually suits your circumstances.

What Happens If A Bogus Car Insurance Claim Is Found To Be Fraudulent?

A fraudulent claim can have serious consequences.

An insurer may reject the claim.

The policyholder could also face problems obtaining insurance in the future.

And in serious cases, it can go further.

Deliberate insurance fraud may lead to legal action or criminal investigation.

So exaggerating a claim isn’t a harmless way to squeeze a little extra money from an insurer.

The potential consequences can far outweigh the amount somebody hoped to gain.

Conclusion

Bogus car insurance claims can create real problems for innocent motorists.

They can lead to disputes, investigations and unnecessary stress.

Fortunately, you’re not powerless.

Good evidence can make an enormous difference.

Photographs, dashcam footage, witnesses and accurate notes can all help establish what really happened.

And if something feels wrong, tell your insurer quickly.

Don’t assume a suspicious claim will simply disappear.

At the same time, don’t let fear of fraud stop you making a legitimate claim when you need to.

That’s exactly what insurance exists for.

The bottom line?

Protect yourself, keep good records and never assume your renewal price is the best available.

Comparing Car Insurance carefully could still help you find cheaper cover without sacrificing the protection you actually need.

Middle Lane Hogging Could Cost You Points

Introduction

Middle lane hogging…

Few motorway habits cause more frustration than a driver sitting unnecessarily in the middle lane.

You may approach safely from behind while travelling in the left lane.

Then comes the dilemma.

Should you cross two lanes to overtake them?

Or should you continue forward and pass on their left?

The second option may feel justified.

However, an unsafe undertaking manoeuvre could result in a fine, penalty points and higher Car Insurance costs.

This guide explains:

  • What middle lane hogging means
  • Why it disrupts motorway traffic
  • Whether undertaking is illegal
  • What penalties drivers could face
  • How penalty points may affect Cheap Car Insurance
  • How to respond safely without making the situation worse

Another driver may cause the frustration, but your reaction could leave you paying for it.

What Is Middle Lane Hogging?

Middle lane hogging happens when a driver remains in the middle lane without overtaking another vehicle.

Drivers should normally use the left lane when the road ahead remains clear.

The middle and outside lanes allow motorists to pass slower traffic.

After completing an overtake, drivers should return to the left when it becomes safe.

Simple enough.

Yet motorists ignore or misunderstand this rule every day.

Some drivers believe the middle lane feels safer.

Others avoid moving left because they expect to meet another slower vehicle eventually.

Meanwhile, distracted drivers may simply stop noticing that the left lane has become empty.

Whatever the reason, unnecessary middle lane driving can obstruct traffic and provoke risky reactions.

Drivers comparing car insurance options should remember that motoring offences can narrow their choices later.

Can Middle Lane Hoggers Receive Penalty Points?

Yes.

Police may treat persistent middle lane hogging as careless or inconsiderate driving.

A less serious offence could result in a fixed penalty and three licence points.

More serious cases may proceed to court.

Therefore, middle lane hogging is not merely irritating.

It can become a motoring offence.

But here is where things get complicated.

The driver attempting to pass the lane hogger could also land in trouble.

Why Does Middle Lane Hogging Cause Congestion?

A middle lane hogger can make a three-lane motorway function more like a two-lane road.

Imagine that you are travelling in the left lane.

A slower vehicle sits ahead in the middle lane, despite the inside lane remaining clear.

To overtake conventionally, you must move into the middle lane.

Then you must move again into the outside lane.

After passing, you complete the same journey back towards the left.

One poorly positioned vehicle has forced several unnecessary lane changes.

And that changes everything.

Every lane change requires observation, signalling, judgement, and sufficient space.

Consequently, unnecessary lane changes create more opportunities for hesitation, blind-spot mistakes, and sudden braking.

Traffic also begins to bunch behind slower vehicles.

Meanwhile, faster motorists crowd into the outside lane.

As a result, the motorway carries traffic less efficiently.

The problem does not end there.

Middle lane hogging regularly provokes anger and impatience.

Drivers may begin tailgating.

Others flash their headlights or repeatedly sound the horn.

Some motorists accelerate beyond the speed limit.

Others remain in the left lane and undertake.

Unfortunately, a few seconds of frustration can create financial consequences lasting several years.

That can make finding very cheap car insurance considerably harder.

Is Undertaking A Middle Lane Hogger Illegal?

Many motorists assume that passing any vehicle on the left automatically counts as an illegal undertaking.

The reality carries more nuance.

The Highway Code advises drivers not to overtake on the left.

It also warns motorists against moving left specifically to pass another vehicle.

Therefore, deliberately changing into the inside lane, accelerating past, and moving right again could be viewed as careless driving.

Here is the crucial distinction.

During congestion, different lanes often travel at slightly different speeds.

In slow-moving queues, motorists may remain in their lane when it moves faster than traffic on the right.

Keeping pace with congested traffic differs from deliberately changing lanes to undertake.

Speed matters.

Road conditions matter.

Your distance from other vehicles matters too.

Above all, police will consider whether the manoeuvre created unnecessary danger.

What If You Are Already In The Left Lane?

This situation causes the greatest confusion.

You may already be travelling correctly in the left lane when you approach a slower middle lane driver.

May not have moved left to undertake them.

You are simply catching up.

So, what should you actually do?

Continuing past at motorway speed may still carry legal risk outside congested conditions.

The safest response usually involves completing a conventional overtake on the right.

Check your mirrors.

Assess the traffic around you.

Then move across one lane at a time when suitable gaps appear.

After passing, return to the left when it becomes safe.

Yes, this can feel unfair.

You are following the rules while the middle lane hogger is not.

Nevertheless, another driver’s mistake does not excuse careless driving.

Two wrongs will not protect your licence.

What Penalties Could Undertaking Carry?

Undertaking does not attract one automatic penalty in every situation.

Instead, the consequences depend on the manner of driving.

Police may deal with an unsafe pass as careless or inconsiderate driving.

A less serious offence could bring a £100 fine and three penalty points.

However, aggressive lane changes, excessive speed, or dangerous passing may lead to court proceedings and heavier penalties.

This is the part many drivers overlook.

Penalty points may also increase future insurance premiums.

Insurers consider motoring convictions when assessing the likelihood of a future claim.

Consequently, drivers with points may receive fewer competitive quotations.

They may also struggle to secure the cheapest car insurance available before the offence.

That makes one impatient decision surprisingly expensive.

Drivers should always disclose relevant convictions when comparing cheap car insurance.

Failing to answer an insurer’s questions accurately could create serious problems during a later claim.

Motorists facing a higher renewal price can also explore five ways to save money on car insurance.

However, prevention remains cheaper than repairing the damage afterwards.

And the financial impact may last much longer than the original journey.

A conviction could influence several renewals before it stops affecting quotations.

Therefore, staying calm may protect both your licence and your bank balance.

Drivers unhappy with their renewal price should compare alternatives before they switch car insurance.

How Should You Respond To A Middle Lane Hogger?

The safest response is simple.

Stay calm and complete a conventional overtake on the right when traffic conditions allow.

Check your mirrors carefully.

Signal before changing lanes.

Then move across one lane at a time, rather than cutting sharply through traffic.

Once you have passed the slower vehicle, return to the left when it becomes safe.

Here is what matters most.

Another driver’s poor lane discipline does not excuse dangerous behaviour from you.

Avoid tailgating, speeding, or repeatedly flashing your headlights.

Likewise, never brake-check another vehicle or use the hard shoulder to pass.

These reactions can quickly turn a frustrating situation into a serious collision.

They may also leave you facing penalty points, a fine, or an insurance claim.

Could Points Increase Your Car Insurance?

Penalty points can affect the price of Car Insurance because insurers use driving history when assessing risk.

However, the increase will vary between providers.

Some insurers may charge more.

Others may apply a larger excess or offer fewer policy options.

Therefore, comparing quotations becomes especially important after a motoring conviction.

Always answer questions about points and convictions honestly.

Providing incomplete information may produce a cheaper initial quotation, but it could cause problems during a later claim.

Cheap today can become expensive tomorrow.

Drivers looking for alternative cover may want to explore telematics car insurance.

A telematics policy may reward careful driving, although savings are never guaranteed.

You should also compare the actual cover provided, rather than choosing the lowest number on the screen.

Our guide to comprehensive versus third-party insurance explains the main differences.

Conclusion

Middle lane hogging is frustrating because it disrupts traffic and forces other motorists to make unnecessary lane changes.

However, undertaking aggressively may create an even greater problem.

A moment of impatience could lead to points, a fine, and higher Car Insurance premiums.

Do not let a few seconds of frustration become years of extra expense.

Keep a safe distance.

Overtake on the right when conditions allow.

Then return to the left once you have safely passed.

The middle lane hogger may be driving badly.

Nevertheless, protecting your licence, your passengers, and your ability to find Cheap Car Insurance matters far more than proving a point.

E-Bike Injury Claims Push UK Car Insurance Costs Above £110 Million

Introduction

E-bike and e-scooter injury claims have exceeded £110 million.

This creates another potential cost pressure for motorists searching for affordable Car Insurance.

E-Bike Injury Claims Could Push Up Car Insurance Costs

Electric bikes and e-scooters have transformed short urban journeys.

They are convenient, relatively inexpensive, and increasingly common.

However, their growing popularity has created an expensive problem.

Claims involving e-bikes, e-scooters, and similar vehicles have now cost almost £111 million.

And ordinary motorists may ultimately help pay the bill.

Here is why.

The Motor Insurers’ Bureau compensates eligible victims injured by uninsured or untraced road users.

That includes some collisions involving illegally ridden e-scooters and non-compliant electric bikes.

However, the MIB does not generate its own money.

UK motor insurers fund it through an annual levy.

Insurers then recover their wider costs through the premiums paid by customers.

Consequently, uninsured micromobility collisions can affect everyone searching for Cheap Car Insurance.

That does not mean one e-scooter crash will immediately increase your renewal price.

Car insurance pricing is far more complicated.

Nevertheless, higher industry claims costs place additional pressure on insurers.

Those costs must eventually be absorbed somewhere.

How Much Have Micromobility Claims Cost?

Claims involving e-bikes and e-scooters reportedly cost approximately £108 million between 2015 and May 2026.

Including e-unicycles and mobility scooters takes the total to almost £111 million.

Moreover, claim numbers increased by 73% between 2023 and 2025.

And the final cost could rise further.

Serious injury claims often remain open for several years.

Doctors may need time to assess long-term care, rehabilitation and employment needs.

Therefore, today’s estimate may not represent the final amount paid.

Some victims may also submit claims months or years after the collision.

That means recent incidents could create further liabilities for insurers.

Why Are E-bike Injury Claims Increasing?

More people now use electrically powered personal transport.

E-bikes have become popular among commuters, delivery riders, and people making shorter journeys.

Private e-scooters are also widely available from shops and online retailers.

Yet availability does not mean they can legally be used everywhere.

Privately owned e-scooters remain illegal on public roads, pavements, and other public land.

They may generally only be ridden on private land with the owner’s permission.

That distinction catches many riders out.

Some people assume a product sold openly in Britain must be legal on British roads.

Unfortunately, that assumption can have serious consequences.

E-scooters are treated as motor vehicles under UK law.

Therefore, somebody riding privately owned e-scooters publicly will usually be riding without valid insurance.

Electric bikes create a slightly different issue.

Most standard electric bikes are legal.

However, modified or high-powered models may fall outside Electrically Assisted Pedal Cycle rules.

A compliant electric bike must generally have pedals and a motor rated no higher than 250 watts.

Electrical assistance must also stop at 15.5mph.

Anything more powerful may legally be treated as a motorcycle or moped.

Registration, licensing, and insurance requirements may then apply.

What Is The Motor Insurers’ Bureau?

The Motor Insurers’ Bureau helps compensate victims of uninsured and hit-and-run road users.

Without it, an injured pedestrian could have no realistic route to compensation.

For example, an e-scooter rider may have no insurance, income, or assets.

Although the victim could pursue the rider personally, the rider may be unable to pay.

The MIB provides an important financial safety net.

However, motor insurers fund that safety net.

Insurers ultimately collect that money from motorists through insurance premiums.

Put simply:

Responsible drivers may collectively fund compensation for collisions caused by uninsured riders.

Micromobility claims are not the only reason insurance prices rise.

Repair costs, theft, fraud, personal injuries, and expensive vehicle technology also influence premiums.

Nevertheless, almost £111 million represents a meaningful additional expense.

Drivers should therefore avoid automatically accepting expensive renewals.

Comparing providers and understanding different car insurance options can help motorists find stronger value.

However, the lowest headline price is not always the cheapest long-term choice.

A very high voluntary excess may reduce the premium.

Yet it could make a future claim unaffordable.

Our guide covering five ways to save money explains how drivers can reduce costs without weakening their protection.

The Serious Injuries Behind The E-bike Injury Claims Figures

The £111 million figure represents far more than administrative costs.

Claims have involved traumatic brain injuries, complex fractures, and serious ligament damage.

Some victims have required surgery and lengthy rehabilitation.

Others have lost income, independence, or career opportunities.

But the impact rarely stops with the victim.

Relatives may need to reduce work or become full-time carers.

Homes may require expensive adaptations.

Mental health difficulties can continue after physical injuries have healed.

Consequently, one severe injury claim can cost millions of pounds.

Compensation may need to cover decades of treatment, care, equipment, and lost earnings.

That explains why claim costs can rise quickly, even when incident numbers appear relatively modest.

Severity matters just as much as volume.

Ultimately, preventing collisions would benefit victims, riders, and everyone paying for Car Insurance.

Why Uninsured E-Scooters Create A Serious Problem

Private e-scooters cannot currently be insured for normal public-road use.

Therefore, anyone riding one on a road, pavement, or in a public park is generally riding illegally.

Government-approved rental scooters are different.

These are insured through authorised trial schemes and may be used within designated areas.

Here is the crucial distinction.

Buying a private e-scooter is legal.

Riding it publicly is not.

Private models may only be ridden on private land with the landowner’s permission.

Nevertheless, many riders either misunderstand or ignore this restriction.

According to research highlighted by the MIB, more than half of UK adults were unaware of the law.

That confusion leaves pedestrians and other road users exposed.

When an uninsured rider causes a serious collision, the victim may need to claim through the MIB.

Consequently, the cost can return to the wider motor insurance market.

What Penalties Could E-Scooter Riders Face?

Illegal e-scooter use carries many of the same consequences as uninsured driving.

Police may seize the scooter.

Riders may also receive a fine and penalty points on their driving licence.

Court action could result in further penalties or a driving ban.

And there is more.

Someone without a licence cannot necessarily avoid the points.

The DVLA may create a driving record so those points appear when that person applies for a licence later.

A conviction could also make future Car Insurance more expensive.

Insurers often consider motoring offences when calculating risk.

Therefore, one illegal journey could affect premiums long after the scooter has disappeared.

Anyone causing an injury may also face personal liability.

That could mean paying compensation for treatment, lost income, and continuing care.

The financial consequences could last for decades.

A cheap journey can become extraordinarily expensive when a rider ignores the law.

Could These E-bike Injury Claims Increase Your Premium?

Micromobility claims will not determine your insurance price on their own.

However, they add to the overall cost insurers must manage.

Your individual premium still depends on your vehicle, postcode, age, occupation, and driving history.

Annual mileage and previous claims also matter.

Even so, wider claims inflation affects the entire market.

Insurers cannot absorb rising costs indefinitely without changing prices.

That is why motorists should compare quotes rather than automatically accepting a renewal.

Those considering different protection levels should understand comprehensive versus third-party cover.

Meanwhile, some drivers may reduce costs by choosing telematics car insurance.

But remember:

The cheapest car insurance is not always the policy with the smallest initial price.

Check the compulsory and voluntary excesses.

Review exclusions carefully.

Most importantly, make sure the policy provides the protection you genuinely need.

What Happens Next?

The MIB has called for better public education about e-scooter and e-bike laws.

That is a sensible starting point.

Retailers should also explain where private scooters can legally be ridden.

Meanwhile, riders must check whether modified electric bikes still meet EAPC requirements.

The Government has indicated that it will consult on e-scooter regulation, including possible insurance requirements.

However, private e-scooters remain illegal on public land unless the law changes.

Future regulation could provide clearer rules and better protection for victims.

Until then, riders should not mistake widespread use for legal use.

Conclusion

E-bikes and e-scooters offer convenient, low-cost transport.

However, illegal and uninsured use can cause serious injuries and significant compensation costs.

These claims are not the only reason car insurance prices rise.

Nevertheless, they add further pressure to an already expensive insurance market.

Riders should understand the law before using an e-scooter or modifying an e-bike.

Motorists should also compare policies rather than automatically accepting their renewal.

Finding Cheap Car Insurance still requires more than chasing the lowest number.

It means finding suitable protection at a competitive price.

For further advice, read our guides to:

young driver insurance,

electric vehicle insurance

breakdown cover is worth buying.


Ambulance Red light Rules? The £1,000 Fine UK Drivers Must Avoid

Introduction

Ambulance red light rules..

Flashing blue lights appear behind you, so you move quickly—but one well-intentioned mistake could mean three penalty points and a fine.

In this guide, we explain:

  • What to do when an ambulance approaches
  • Whether you can cross a red light
  • Where and when you should pull over
  • Which dangerous reactions drivers must avoid
  • How a traffic offence could affect your car insurance
  • Why staying calm may protect both your licence and your wallet

What Should You Do When An Ambulance Approaches?

Most drivers instinctively want to clear the road as quickly as possible.

That reaction makes sense.

However, speed is not the priority.

Safety is.

Highway Code Rule 219 tells drivers to consider the emergency vehicle’s route and take appropriate action while obeying traffic signs. (GOV.UK)

In other words, you should help the ambulance pass without creating another dangerous situation.

Ambulance Red Light Rules: Here Is The Crucial Point

The ambulance driver needs you to act predictably, not dramatically.

First, check your mirrors and assess the road ahead.

Then, look for somewhere safe to pull over without blocking a junction, bend or narrow section.

Signal clearly before changing your position.

Afterwards, slow down gradually and leave enough space for the emergency vehicle to pass.

Avoid braking sharply.

A driver behind you may not have seen the ambulance yet.

Likewise, do not stop in the middle of the road unless traffic conditions leave no safer alternative.

You could block the ambulance rather than help it.

And there is another risk

Some drivers panic and mount the kerb.

However, doing so could endanger pedestrians, damage the vehicle or cause a collision.

The Highway Code specifically advises drivers not to endanger themselves, pedestrians or other road users when making space.

Therefore, stay controlled and keep observing your surroundings.

Finding cheap car insurance matters, but protecting your driving record matters too.

One rushed decision can carry consequences long after the ambulance has passed.

Ambulance Red Light Rules: Can You Go Through A Red Light For An Ambulance?

No.

You should not cross the solid white stop line while the traffic signal remains red.

This rule still applies when an ambulance, police car or fire engine waits behind you.

Blue Light Aware advises the first driver in a queue to remain where they are and let the emergency vehicle find another route. That May Feel Completely Wrong

You can hear the siren.

Can see the flashing lights.

You may even feel pressure to move.

Nevertheless, crossing the line could place you directly in the path of pedestrians or traffic entering from another direction.

The emergency driver understands this.

Emergency crews receive specialist training and can use legal exemptions that ordinary motorists cannot use.

Therefore, let the crew decide how to navigate the junction.

Do not enter the junction, edge across the line or move into crossing traffic.

The only clear exception arises when a uniformed police officer directs you to move.

Drivers must follow lawful directions from police officers controlling traffic.

What happens If You Go Through A Red Light For An Ambulance?

Failing to comply with traffic-light signals carries three penalty points.

A court can also impose a maximum fine of £1,000 and may consider disqualification. (GOV.UK)

That does not mean every driver will automatically receive a £1,000 bill.

However, the potential penalty remains serious.

A camera records your vehicle crossing the line.

It does not automatically know that an ambulance was behind you.

Furthermore, points on your licence may affect future car insurance options.

Insurers calculate premiums using numerous risk factors, including driving history and motoring convictions.

Consequently, a moment of panic could make finding the cheapest car insurance more difficult later.

What If The Ambulance Remains Directly Behind You?

Stay calm and remain predictable.

Do not assume that a sounding siren gives you permission to break road rules.

This is where many drivers make the mistake.

They focus entirely on the ambulance and stop watching pedestrians, cyclists and surrounding traffic.

Instead, keep checking every direction.

If the lights change to green, move forward carefully and create space as soon as conditions allow.

If they remain red, stay behind the stop line.

The ambulance may use another lane, move around the traffic or wait until the junction becomes safe.

Although the delay may feel uncomfortable, an unsafe manoeuvre could waste more time.

Worse still, it could cause another emergency.

Drivers searching for very cheap car insurance should remember that avoiding offences remains one of the simplest ways to protect their record.

Ultimately, helping an ambulance does not mean moving at any cost.

It means responding safely, legally and without panic.

**H2 Conclusion

Can You Go Through A Red Light For An Ambulance At A Junction Box?

An approaching ambulance does not cancel yellow box junction rules.

You should only enter when your exit is clear.

Otherwise, you may become trapped inside the box.

And that creates a bigger problem.

Instead of helping the ambulance, you could block its route completely.

The usual right-turn exception still applies.

However, you must only wait when oncoming traffic or another right-turning vehicle prevents you from completing the turn.

Do not follow the vehicle ahead without checking the available space.

Likewise, never enter simply because another driver behind you starts sounding their horn.

Their impatience will not protect you from a penalty.

Can You Use A Bus Lane Or Mount The Kerb?

Drivers sometimes move into a bus lane when blue lights appear behind them.

However, you should not enter a restricted lane unless the signs allow your vehicle to use it.

Bus lanes often contain cameras.

Therefore, entering one at the wrong time could result in a Penalty Charge Notice.

But that is not the only danger.

Cyclists, motorcyclists and buses may already be using the lane.

A sudden movement could cause a serious collision.

Mounting the kerb creates similar risks.

Pedestrians may not expect a car to move onto the pavement, even during an emergency.

Stay on the road and move aside only when it is safe.

A calm response protects everyone.

Ambulance Red Light Rules: How Much Could The Mistake Cost?

The penalty depends on the rule you break.

Crossing a red light can lead to three penalty points and a fine.

A court may impose a maximum fine of £1,000.

Yellow box and bus lane offences usually involve council-issued penalties instead.

However, charges vary between local authorities.

More serious manoeuvres could also lead to allegations of careless or dangerous driving.

Here is why that matters.

The immediate fine may not represent the full cost.

Penalty points and motoring convictions can also influence future car insurance prices.

Insurers consider your driving history when assessing risk.

Consequently, a rushed decision could make finding cheap insurance in the UK more difficult.

You must also answer your insurer’s questions honestly.

Failing to declare requested information could create problems later, particularly when making a claim.

What Do Silent Blue Lights Mean?

An ambulance may sometimes display blue lights without using its siren.

That does not necessarily mean the emergency has ended.

The crew may reduce noise near vulnerable road users, during quieter hours or when traffic cannot safely move.

Therefore, continue watching the vehicle.

Do not make a sudden manoeuvre simply because the siren stops.

The safest approach remains the same.

Stay alert, remain predictable and create space when conditions allow.

Five steps to remember

  1. Stay calm and check your mirrors.
  2. Identify where the emergency vehicle needs to go.
  3. Signal before changing speed or position.
  4. Obey red lights, road markings and restricted lanes.
  5. Move aside only when it is safe and legal.

Frequently asked questions

Do I legally have to move for an ambulance?

You should take appropriate action to help it pass while continuing to follow traffic laws.

Can you go through a red light for an ambulance?

No.

Remain behind the stop line unless a uniformed police officer directs you to move.

Will penalty points increase my insurance?

They may.

The effect depends on the offence, your driving history and the insurer’s pricing rules.

Comparing providers may help you find the cheapest car insurance available for your circumstances.

Conclusion

Stay calm and protect your licence.

Most drivers want to help emergency crews reach their destination quickly.

However, panic can turn good intentions into an expensive mistake.

Do not cross a red light, enter a blocked junction or endanger pedestrians.

Instead, stay calm and let the emergency driver choose the safest route.

One careful decision could protect your licence, your insurance premium and everyone around you.

Driver Fined Again Paying Parking Ticket Using A Mobile Phone While Driving

Introduction

Using a mobile phone while driving is a no-no!

A Guildford driver reportedly received a £200 fine and six penalty points while using her phone to pay an earlier parking penalty.

The timing could hardly have been worse.

She was sitting in stationary traffic when an unmarked police vehicle pulled alongside her.

Moments later, she realised officers had seen the phone in her hand.

The incident offers a clear warning for UK motorists.

Being stuck in traffic does not usually make handheld phone use legal.

A brief mistake can also affect your licence, your finances and potentially your future Car Insurance.

Using A Mobile Phone While Driving To Pay A Fine Costs Driver £200

The incident took place in Guildford, Surrey.

Footage shared by Surrey Roadsafe showed the woman using her phone behind the wheel.

However, she was not reportedly making a casual call.

Instead, she appeared to be paying a parking fine.

That detail makes the story memorable.

It does not make the phone use lawful.

At the time, her vehicle was sitting in stationary traffic.

She may therefore have believed that handling the device carried little risk.

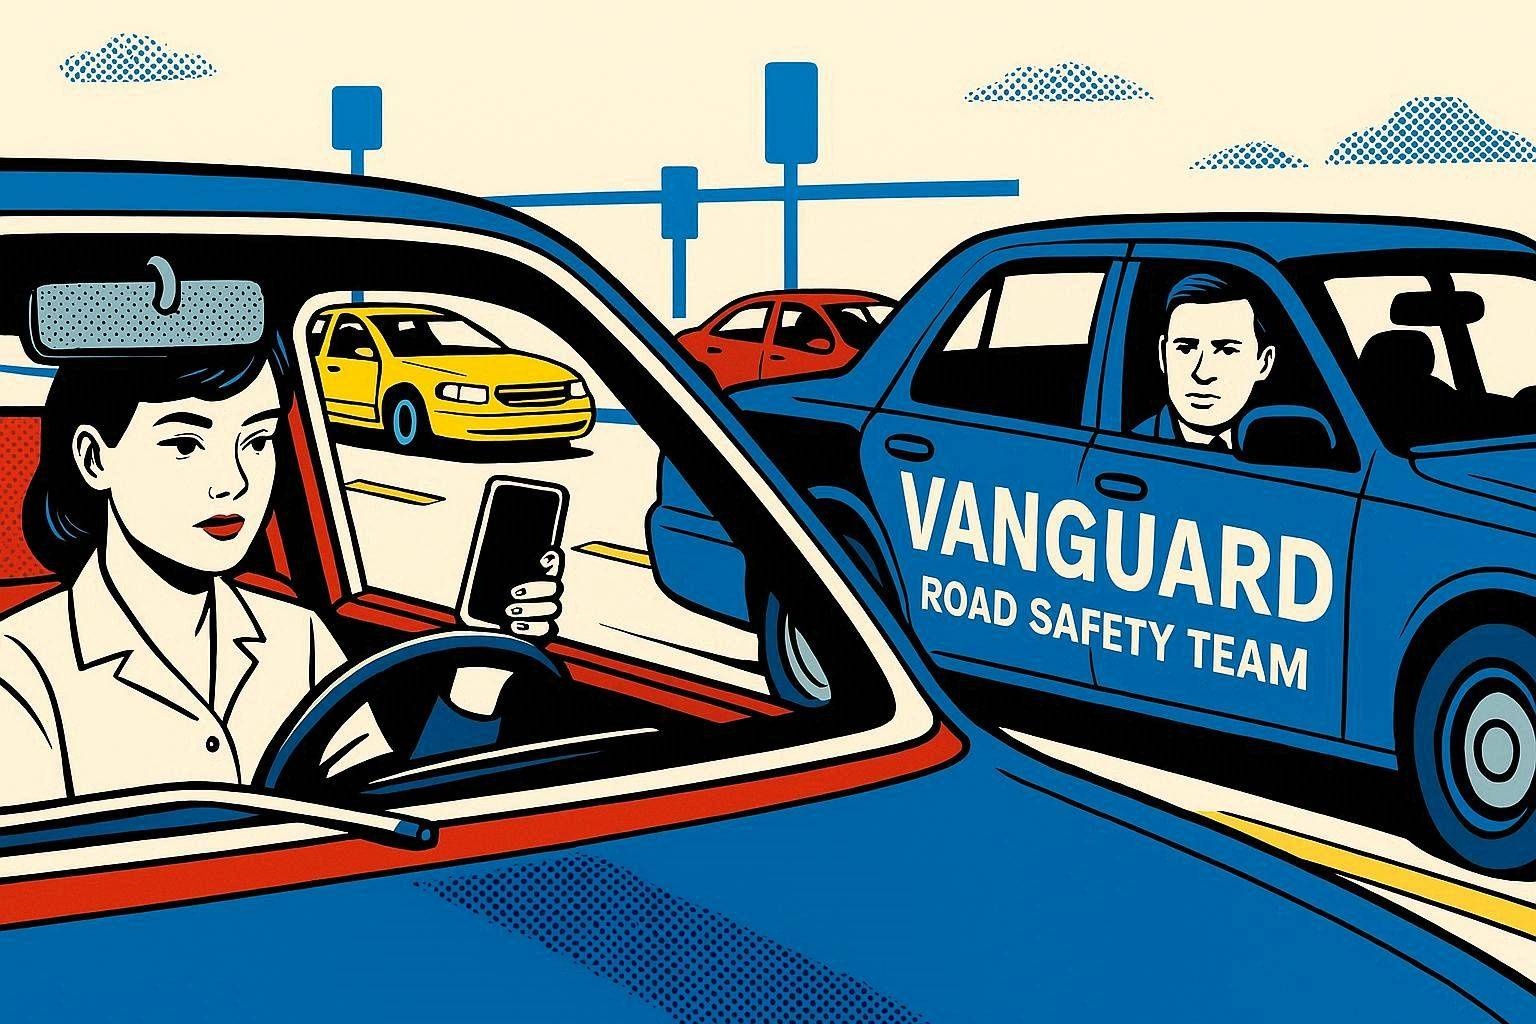
Then an unmarked Vanguard Road Safety Team vehicle pulled alongside her.

The specialist unit operates within Surrey Police.

Officers could reportedly see the phone in her hand.

The woman then looked across and appeared to realise who was watching.

That was when the situation changed.

She was issued with a Traffic Offence Report.

The outcome was another £200 fine and six penalty points.

In other words, paying one penalty helped create a second, more serious problem.

A payment can wait. Six penalty points may follow you for years.

Why Stationary Traffic Still Counts As Driving

Here is the crucial point.

A car does not need to be moving for the handheld phone rules to apply.

Drivers can still commit an offence by using a mobile phone while waiting at traffic lights.

The same applies when queuing in congestion.

Therefore, saying “I was not moving” does not automatically provide a defence.

Many drivers misunderstand this rule.

They see a red light or traffic jam as a safe opportunity to check their screen.

After all, the wheels have stopped.

The journey, however, has not ended.

You remain responsible for the vehicle while waiting for traffic to move.

Your attention should stay on nearby cars, pedestrians, cyclists and changing road conditions.

A queue can also begin moving without warning.

That is why the safest rule remains simple.

Wait until you have parked properly before handling the phone.

What Counts As Handheld Phone Use?

This is where many motorists get caught out.

The offence is not limited to calls or text messages.

It can also cover:

  1. Opening an app
  2. Checking social media
  3. Taking photographs
  4. Choosing music
  5. Entering navigation details
  6. Making an online payment

Therefore, paying for parking is not automatically treated differently from using another app.

The purpose may feel sensible.

The method remains the problem.

One quick tap can easily become several.

Then a message appears.

Next, the driver looks down for longer than intended.

That is how a small distraction grows.

Are There Any Exceptions To Using A Mobile Phone While Driving?

Yes, but the exceptions are narrow.

Drivers may use a handheld phone to call 999 or 112 during a genuine emergency when stopping is unsafe.

Certain contactless payments may also be allowed while the vehicle remains stationary.

For example, this may apply at a drive-through or toll terminal.

However, it does not provide general permission to browse a parking app in traffic.

Remote parking functions can also fall within a specific exception.

Again, that does not allow unrelated phone use behind the wheel.

So, here is the safest approach.

Unless a clear exception applies, put the phone down until you have parked.

What Is The Penalty For Using A Mobile Phone While Driving?

The standard penalty for illegal handheld phone use is £200 and six penalty points.

That is a serious punishment for a few seconds of distraction.

However, the fine may not be the largest long-term cost.

The points can remain relevant when drivers apply for future insurance.

They can also create immediate problems for newly qualified motorists.

Why Six Points Matter For New Drivers

Here is where the situation becomes even more serious.

Drivers who receive six points within two years of passing their test can have their licence revoked.

One mobile phone offence may therefore be enough.

The driver may need to apply for another provisional licence.

They may also need to retake both driving tests.

That means more lessons, more fees and more disruption.

For many young motorists, losing a licence can also affect work or education.

And then there is insurance.

New drivers already tend to face higher prices.

A mobile phone conviction can make finding cheap car insurance for young drivers even more difficult.

That is a considerable price for a task that could have waited.

How Can Penalty Points Affect Car Insurance?

Insurers consider driving convictions when calculating risk.

Therefore, six points may increase the price of your next policy.

The exact increase will vary.

Your age, vehicle, location and claims history will still matter.

Even so, some insurers may offer fewer options after a conviction.

Others may charge a higher premium or excess.

This is why drivers should never assume their renewal remains competitive.

Instead, compare several car insurance options before accepting a price.

The difference between insurers can become larger after penalty points.

And this matters.

The cheapest policy before a conviction may not remain the cheapest afterwards.

Do You Need To Tell Your Insurer?

Drivers should check their policy documents carefully.

Some insurers require notification during the policy term.

Others ask about convictions when the policy renews.

Either way, you must answer every question honestly.

Failing to disclose relevant information could create problems later.

For example, an insurer may investigate when you make a claim.

Incorrect details can also affect whether cover remains valid.

So, do not hide the offence to obtain a lower quote.

That is not genuine very cheap car insurance.

It is a risk that could become far more expensive.

Can You Still Find Cheaper Cover With Points?

Yes, although you may need to search more carefully.

Start by comparing quotes from several providers.

Next, check that every conviction detail is accurate.

Then review the parts of the policy you can control.

For example:

  • Choose a car from a lower insurance group
  • Review your annual mileage honestly
  • Improve the vehicle’s security
  • Avoid unnecessary optional extras
  • Consider a higher voluntary excess you can genuinely afford
  • Compare quotes before your renewal date

These steps will not erase the conviction.

However, they may help reduce the overall cost.

You can also read our guide to five ways to save money on car insurance.

The important thing is to compare like-for-like cover.

A lower price is not useful when the policy removes protection you actually need.

How Should Drivers Pay For Parking Safely?

The safest option is simple.

Park properly before using the phone.

Do not complete a payment while waiting at traffic lights.

Do not hold the device while sitting in congestion.

Instead, finish the payment before beginning the journey.

Alternatively, ask a passenger to use the app.

If necessary, pull over somewhere legal and safe.

A parking payment may feel urgent.

Usually, it can wait for a few minutes.

Six penalty points are much harder to undo.

Using A Mobile Phone While Driving: What Should Drivers Learn From This Case?

The Guildford incident highlights a common misunderstanding.

Stationary traffic does not normally make handheld phone use legal.

The reason for using the phone does not automatically matter either.

Paying a penalty may sound responsible.

Yet the driver still handled the device behind the wheel.

That single decision reportedly created another fine and six points.

It may also affect the cost of her future insurance.

Here is the real lesson.

A phone task can wait.

Your licence may depend on it.

Conclusion

The driver in Guildford reportedly tried to settle one penalty and received another.

Unfortunately, the second offence carried far more serious consequences.

A £200 fine hurts immediately.

Six penalty points can create problems for years.

They may threaten a new driver’s licence.

They may also make the cheapest car insurance harder to find.

So, resist the temptation to use your phone in stationary traffic.

Wait until you have parked safely.

Then make the payment, send the message or change the route.

A few minutes of patience could protect your licence and your wallet.

For related guidance, read our articles on:

mobile phone offences and losing your licence,

driving convictions and insurance and

what can invalidate car insurance.

Car Insurance Warning: The Yellow Kerb Lines Many UK Drivers Still Misunderstand

Introduction

Why These Small Yellow Kerb Lines Matter.

Most UK drivers know what double yellow lines mean.

Or at least, they think they do.

But the small yellow marks painted on the kerb are different.

They are not about ordinary parking.

They are about loading and unloading.

And misunderstanding them can cost you.

This guide explains what yellow kerb lines mean, why drivers confuse them, and how small mistakes on the road can lead to bigger costs.

It also explains why careful driving habits matter when comparing Car Insurance.

The Yellow Kerb Lines Many Drivers Miss

You can drive for years and still miss them.

Those short yellow lines painted vertically on the kerb are easy to ignore.

They are not as obvious as double yellow lines on the road.

They are not as familiar as a no-entry sign.

But they matter.

Here’s the catch.

Yellow kerb marks are loading restrictions.

They tell drivers whether they can stop to load or unload goods.

That could affect delivery drivers.

It could affect tradespeople.

It could also affect ordinary motorists collecting something heavy from a shop.

So, if you stop beside them without checking the signs, you may be taking a risk.

And not a clever one.

What Do Yellow Kerb Lines Mean?

Yellow kerb lines are often called loading marks.

Some people call them kerb blips.

They show restrictions on loading and unloading.

A single yellow kerb line usually means loading is restricted at certain times.

A double yellow kerb line usually means loading and unloading are banned.

That sounds simple.

But this is where drivers get caught.

A yellow line on the road and a yellow mark on the kerb do not mean the same thing.

The road line usually deals with waiting.

The kerb mark deals with loading.

Different rule.

A different mistake.

Different fine.

So, before you stop, look at the kerb.

Then look for the nearby sign.

That sign should tell you when the loading restriction applies.

If you want Cheap Insurance UK, small details like this may seem boring.

However, boring details are often the ones that save money.

Parking, Waiting, Loading: Why The Difference Matters

Most people use “parking” to mean any kind of stopping.

But the rules are more specific.

Parking usually means leaving the vehicle stationary.

Waiting can still happen while you are sitting inside the car.

Loading means actively moving goods to or from the vehicle.

That difference matters.

For example, sitting in the car while someone goes into a shop may still count as waiting.

Keeping the engine running does not automatically help.

Putting your hazard lights on does not make it legal either.

Now for the important bit.

Loading is not the same as waiting.

If you are genuinely moving heavy goods, stock, tools, or equipment, loading may be allowed in some places.

But it usually needs to be necessary and continuous.

You cannot just stop, wander off, and call it loading.

That is where many drivers lose the argument.

And the same logic applies to Cheap Car Insurance.

Assumptions can be expensive.

Assuming a road marking means one thing can lead to a fine.

Assuming your policy covers something can lead to a nasty surprise.

Do Double Yellow Lines Always Ban Loading?

No.

This is the part many motorists misunderstand.

Double yellow lines usually mean no waiting at any time.

But they do not always ban loading.

In some places, you may load or unload on double yellow lines if it is safe, necessary, and continuous.

However, there is a big exception.

If yellow kerb marks show a loading ban, loading is not allowed.

That is why the kerb matters.

Not just the road.

A single yellow kerb mark usually means loading is restricted during certain hours.

A double yellow kerb mark usually means no loading at any time.

So, if you see double yellow lines on the road and double yellow marks on the kerb, do not assume you can stop to unload.

That quick two-minute stop may not be worth it.

Why This Matters For Car Insurance

A simple parking or loading fine is not the same as a car insurance claim.

That is important.

But road awareness still matters.

Drivers who miss signs, stop in risky places, or make rushed decisions can create problems for themselves.

A poor stopping choice could block traffic.

It could cause another driver to swerve.

It could lead to damage, stress, or a dispute.

That is when a small mistake can become much bigger.

So, while kerb markings may not directly decide your premium, they are part of a wider picture.

Careful drivers tend to avoid avoidable problems.

They read the road.

Check the details.

They do not guess.

That same mindset helps when comparing the Cheapest car insurance.

Because the cheapest policy is not always the smartest policy.

The better question is this.

What is the cheapest suitable cover for the way you actually drive?

That is where real savings begin.

The Small Details That Can Cost Drivers Money

Car ownership is full of small costs.

Some are obvious.

Fuel.

Repairs.

MOTs.

Insurance.

Others creep up quietly.

A penalty charge.

A missed renewal date.

A policy add-on you never needed.

A higher monthly payment because you did not pay annually.

A claim that could have been avoided.

That is why road awareness matters.

It is not just about being a “better driver”.

It is about avoiding unnecessary cost.

And when you are looking for very cheap car insurance, that mindset helps.

Because cheaper driving is not only about finding a low quote.

It is also about reducing the chances of expensive problems.

Here’s the uncomfortable bit.

Many drivers only think about insurance when the renewal email arrives.

By then, they are already under pressure.

They rush.

Skim.

They accept.

Or they compare badly.

That can mean paying more than needed.

It can also mean choosing cover that does not properly fit how they drive.

That is why it makes sense to review your options before renewal day.

You can also read our guide on 5 ways to save money if cutting costs is your main goal.

Why Delivery Drivers Often Know These Rules Better

Delivery drivers tend to understand kerb markings better than most motorists.

They have to.

A missed loading sign can ruin a route.

A badly chosen stop can lead to a fine.

A loading ban can turn a simple drop-off into a problem.

But ordinary drivers get caught too.

You might be collecting furniture.

Dropping off boxes.

Helping someone move.

Picking up tools.

Taking a heavy item into a flat.

And you might think:

“I’m not parking. I’m only loading.”

That may sound reasonable.

But the kerb marking may say otherwise.

If there are double yellow kerb marks, loading may be banned completely.

No long argument.

magic hazard lights.

No “I was only two minutes”.

The rule is already there.

And that is the wider lesson.

The detail you ignore is often the detail that costs you.

The same can be true with insurance.

If you use your car for work, deliveries, client visits, or business travel, standard cover may not be enough.

In that case, it is worth understanding business car insurance before assuming you are covered.

The Cheapest Car Insurance Is Not Always the Best Fit

Everyone wants the Cheapest car insurance.

That is normal.

Nobody wants to overpay for cover they hope never to use.

But cheapest is not always the same as best value.

There is a difference.

A policy can look cheap because the excess is high.

It can look cheap because the cover is limited.

Can look cheap because certain uses are excluded.

It can also look cheap because the driver has not checked the details.

That is where problems start.

So, when comparing Car Insurance, look beyond the price.

Check the excess.

The cover level.

Whether commuting is included.

Check named drivers.

Optional extras.

Check whether modifications need declaring.

Also, think about the car itself.

Some vehicles are simply cheaper to insure than others.

If you are buying a car and want to keep costs down, our guide to the cheapest cars to insure is a useful place to start.

Because insurance savings often begin before you buy the car.

Not after.

How UK Drivers Can Stay Out Of Trouble

The good news?

This is easy to improve.

You do not need to memorise every road marking in Britain.

You just need better habits.

Start with the kerb.

Then check the sign.

Then ask yourself what you are actually doing.

Are you parking?

Or are you waiting?

Are you genuinely loading?

Or are you just hoping nobody notices?

That last one is risky.

And usually not worth it.

Use this quick checklist:

  1. Check the road markings.
  2. Check the kerb markings.
  3. Look for nearby signs.
  4. Do not rely on hazard lights.
  5. Keep loading continuous if it is allowed.
  6. Avoid stopping where you could obstruct traffic.
  7. Compare insurance before your renewal date.

That final point matters more than many drivers realise.

If your renewal price has jumped, do not accept it blindly.

Look at your options.

You may be able to switch car insurance and save money.

Some drivers may also benefit from telematics car insurance, especially if they drive safely and want their habits to count.

Why This Matters More In Busy UK Towns And Cities

Kerb restrictions are common in busy places.

High streets.

Shopping areas.

Town centres.

Bus routes.

Narrow roads.

Delivery zones.

Outside flats and offices.

These are exactly the places where drivers feel pressure to stop quickly.

That pressure leads to mistakes.

A passenger is waiting.

A shop collection is ready.

Traffic is building behind you.

There is nowhere obvious to pull in.

So you stop.

Just for a moment.

But that moment can still count.

And if the signs are against you, it can still cost you.

This is one reason urban drivers need to be extra careful.

More traffic usually means more decisions.

More decisions mean more chances to get something wrong.

It can also mean higher insurance costs in some areas.

If you want to understand the bigger picture, read our guide on why car insurance is expensive in the UK.

Conclusion

Small Yellow Lines, Bigger Money Lessons

Yellow kerb lines are easy to miss.

But they are not meaningless.

Single yellow kerb marks usually mean loading is restricted at certain times.

Double yellow kerb marks usually mean loading and unloading are banned.

So, before you stop, check the kerb.

Then check the sign.

That small habit can help you avoid unnecessary fines, stress, and disputes.

The same thinking applies to Car Insurance.

Do not guess.

Don’t rush.

Do not assume your renewal is the best deal.

Compare your options, check the details, and look for cover that suits the way you actually drive.

For more help, read our guides on:

car insurance excess,

third party vs fully comprehensive cover, and

how insurers calculate insurance.

Car Insurance Warning: World-First Laughing Gas Breathalyser Could Change How UK Drivers Are Caught

Introduction

Police are trialling a world-first laughing gas breathalyser in southern England, and therefore, this is not just another roadside crackdown.

For UK drivers, it could become a serious Car Insurance warning.

If nitrous oxide use becomes easier to detect, then risky drivers may face more than prosecution.

They could also face higher premiums, refused claims, cancelled cover, and fewer chances of finding Cheap Car Insurance.

This article explains:

  • Why police are testing a laughing gas breathalyser
  • How nitrous oxide can affect driving risk
  • Why drug-driving can damage Car Insurance options
  • How young drivers could face higher costs
  • Why the Cheapest car insurance usually rewards safer behaviour

What Is The Laughing Gas Breathalyser Trial?

Police in Hampshire, the Isle of Wight, and Thames Valley are testing a roadside nitrous oxide breathalyser.

That sounds technical.

However, the idea is simple.

The device aims to show whether a driver has recently inhaled laughing gas.

Until now, that has been difficult to prove quickly.

So, although officers may suspect nitrous oxide use, evidence has not always been easy to collect.

Here’s where things change.

If police can detect laughing gas at the roadside, more drivers may face drug-driving action.

And, as a result, Car Insurance consequences may follow.

Laughing Gas Breathalyser: Why This Matters For Insurance

Insurers do not just look at your car.

They look at your behaviour.

Look at risk.

They look at anything that suggests you may cost them money.

Therefore, a drug-driving offence can become more than a legal problem.

It can become a pricing problem.

A driver who once found Very cheap car insurance may suddenly face higher quotes.

Some insurers may still offer cover.

Others may walk away.

Either way, the market can shrink fast.

Why Police Are Taking Nitrous Oxide Seriously

Nitrous oxide is often treated casually.

That is the dangerous part.

A few seconds of laughter can still affect judgement, awareness, and reaction time.

On the road, that matters.

A late brake can change everything.

A missed hazard can change everything.

A tiny delay can become a claim, a conviction, or worse.

The real risk is not only the gas. It is the decision to drive afterwards.

And this is where many drivers get caught out.

They think the moment has passed.

However, the consequences may last much longer.

The Insurance Problem Nobody Thinks About First

Most drivers think about police penalties first.

The fine.

The court date.

The possible ban.

However, Car Insurance may hurt later.

A conviction can affect future quotes.

A claim involving impairment can become complicated.

A cancelled policy can make new cover harder to arrange.

And, therefore, the search for Cheap Insurance UK deals can become much more stressful.

That is why drivers should take policy questions seriously.

When comparing car insurance options, accuracy matters.

Not roughly.

Not “close enough”.

Accurately.

Why Young Drivers Could Be Hit Hardest

Young drivers already pay some of the highest premiums in the UK.

So, naturally, any extra risk can hit harder.

A young driver with a clean licence may still struggle to find affordable cover.

Add drug-driving concerns, and the numbers can rise quickly.

This is why UK car insurance for young drivers needs careful planning.

Small mistakes can become expensive.

Big mistakes can become brutal.

And although many young motorists drive responsibly, insurers price risk with limited sympathy.

They look at patterns.

Look at records.

They look at probability.

So, consequently, one reckless incident can follow a driver into future Car Insurance quotes.

How One Bad Decision Can Make Cheap Cover Harder To Find

The Cheapest car insurance usually goes to drivers who look predictable.

Clean licence.

Low risk.

Accurate details.

Sensible mileage.

No avoidable drama.

That may sound boring.

But boring is often cheaper.

Meanwhile, drug-driving creates the opposite signal.

It tells insurers there may be extra risk.

And extra risk usually means extra cost.

It was only once is not much help on a quote form.

Insurers prefer facts.

So, if a driver wants Cheap Car Insurance, they need to protect their record.

Because, ultimately, the cheapest policy rarely comes from explaining mistakes afterwards.

It comes from avoiding them before they happen.

Could A Laughing Gas Incident Affect A Future Claim?

This is where the warning becomes sharper.

If a driver crashes after using nitrous oxide, the insurer may investigate carefully.

They may look at police evidence.

May check the driver’s behaviour.

They may review whether the policy terms were followed.

Therefore, even with comprehensive cover, the claim may not feel simple.

That matters.

Because comprehensive car insurance does not remove every responsibility.

Drivers still need to stay legal.

They still need to answer questions honestly.

They still need to avoid reckless behaviour.

And, crucially, they still need to protect their future Car Insurance record.

Why Comparing Quotes Still Matters

If your renewal price jumps, do not accept it blindly.

That is the expensive mistake.

Instead, compare quotes early.

Check your mileage.

Review your job title.

Look at your excess.

Remove cover you no longer need.

Also, if suitable, consider telematics car insurance.

For some careful drivers, black box cover may help prove safer habits.

However, it will not rescue reckless driving.

It rewards better behaviour.

Not excuses.

Why Enforcement Changes Could Affect Insurance Costs: Laughing Gas Breathalyser

Roadside testing is becoming smarter.

That should make drivers think.

If police can prove more offences, then insurers may see more evidence.

More evidence can mean more convictions.

More convictions can mean higher Car Insurance prices.

It is that simple.

So, although the laughing gas breathalyser trial is still new, the message feels clear.

Risky driving is becoming harder to hide.

And once a driver becomes high risk, finding Cheap Insurance UK deals can become harder.

That is why switching matters too.

If your insurer no longer offers a fair price, you can compare options before renewal.

You can also read more about when to switch car insurance.

Timing can make a difference.

So can accuracy.

And, sometimes, so can patience.

Conclusion

The world-first laughing gas breathalyser trial may sound like a police technology story.

However, for UK drivers, it is also a Car Insurance warning.

If nitrous oxide use becomes easier to detect, then one reckless journey could create years of financial pain.

A driver may face prosecution.

They may face higher premiums.

They may lose access to the Cheapest car insurance deals.

And, in some cases, they may struggle to find affordable cover at all.

Therefore, the safest route is also the cheapest route.

Stay legal.

Drive clearly.

Answer insurance questions accurately.

Then, before accepting a renewal, compare Cheap Car Insurance options and avoid paying more than necessary.

Similar Articles You May Find Useful

For more guidance, read our blogs on

drug-driving and UK car insurance,

what can invalidate your car insurance, and

drivers with points on their licence, as each one explains how one driving mistake can affect your future premiums.

Car Insurance Typo Leaves 86-Year-Old Woman Convicted: The One-Letter Mistake Every UK Driver Must Check

Introduction

A tiny Car Insurance typo can look harmless.

However, one wrong letter can quickly become a serious problem.

That is exactly what happened to an 86-year-old woman.

She bought cover for her Suzuki Splash.

She believed she had followed the law.

Yet, because one letter on her registration number was wrong, her car appeared uninsured.

Then came the shock.

The DVLA contacted her.

A fast-track court process followed.

And, eventually, she received a criminal conviction.

That sounds extreme.

However, it shows how unforgiving car insurance paperwork can become.

Therefore, before UK drivers chase Cheap Car Insurance, they need to check every detail.

Woman, 86, Convicted After Car Insurance Typo Error

An 86-year-old woman believed she had done everything right.

She bought a year’s worth of car insurance through Swinton Insurance.

The policy covered her Suzuki Splash.

At least, that is what she thought.

However, one letter on the registration number was wrong.

An F appeared where an S should have been.

As a result, her car appeared uninsured.

That one-letter mistake triggered a DVLA prosecution.

Here’s the uncomfortable part.

The woman said she believed her car was fully insured from 1 April 2025 to 31 March 2026.

She only realised the problem after receiving a letter about prosecution.

Her niece also wrote to explain the family had found the paperwork error.

“All the paperwork for insurance has been found to be one letter incorrect.”

Even so, the case still went through the Single Justice Procedure.

She received a three-month conditional discharge.

She also had to pay a £26 victim surcharge.

So, although this was not a huge fine, it still meant a criminal conviction.

And that is why this story matters.

Because many UK drivers now search for Cheap Insurance UK, very cheap car insurance, and the cheapest car insurance online.

However, when people rush through forms, mistakes become easier.

One wrong letter.

A wrong digit.

One old postcode.

An incorrect start date.

Suddenly, cheap cover can become stressful cover.

Car insurance depends on exact information.

Your insurer needs the correct registration number.

The DVLA needs the correct vehicle record.

Police systems need the vehicle to show as insured.

The Motor Insurance Database also needs the right details.

Therefore, one typo can break the chain.

That does not always mean someone has acted dishonestly.

However, it can still make a properly insured driver look uninsured.

That is the danger.

A driver may have paid for cover.

They may have received the documents.

They may even have felt completely protected.

However, if the wrong registration appears on the policy, the real vehicle may not show correctly.

So, after buying car insurance, drivers should check the final documents immediately.

Not later.

Immediately.

Especially when using online forms, comparison sites, or quick renewal links.

Speed helps.

However, speed also creates risk.

That is why Very Cheap Car Insurance should never mean careless car insurance.

The Car Insurance Details Every UK Driver Should Check

Before filing your policy away, check the boring details.

Because those boring details protect you.

Start with these:

  1. Vehicle registration number.
  2. Make and model.
  3. Policy start date.
  4. Your address.
  5. Overnight parking location.
  6. Annual mileage.
  7. Main driver.
  8. Named drivers.
  9. Occupation.
  10. Previous claims.
  11. Driving convictions.
  12. Modifications.

If anything looks wrong, contact the insurer straight away.

Ask them to correct it.

Then ask for written confirmation.

Also, keep screenshots, emails, and updated documents.

Because, if a question comes up later, evidence matters.

This is especially important when you switch car insurance near renewal time.

A wrong start date can cause problems.

A missed payment can cause problems.

And, as this case shows, one wrong letter can cause problems too.

Why Cheap Car Insurance Still Needs Accurate Details

Everyone wants cheaper cover.

That is completely understandable.

Car insurance has become a painful cost for many UK drivers.

Therefore, it makes sense to compare quotes, challenge renewals, and look for better deals.

However, cheap should never mean rushed.

And cheap should never mean vague.

When insurers calculate a price, they look at risk.

Your postcode matters.

Occupation matters.

Your mileage matters.

Claims history matters.

Your vehicle matters.

Even where you park overnight can change the quote.

So, if one detail is wrong, the policy may not reflect your real situation.

That can become a problem later.

Not always.

But sometimes.

And sometimes is enough.

Here’s the key point.

The cheapest car insurance is only valuable if it actually protects you.

A low price means very little if a mistake leads to delays, questions, or disputes.

Therefore, UK drivers should look for affordable cover and accurate cover.

That is the safest combination.

Could A Car Insurance Typo Affect A Claim?

A small typo does not automatically mean an insurer will reject a claim.

However, it can create questions.

And questions can slow everything down.

For example, an insurer may ask whether the error affected the price.

They may ask whether they would have offered the same cover.

They may also ask whether the mistake looked accidental or careless.

That is why drivers should not ignore errors.

A wrong registration number can create one issue.

A wrong address can create another.

An undeclared modification can create another.

Meanwhile, incorrect named driver information can also cause serious problems.

So, although a typo may look minor, it can still create friction.

And friction is the last thing you want after an accident.

That is why it is worth reading your documents properly.

Not just the price.

Nor just the excess.

Not just the monthly payment.

The details matter.

If you want Cheap Insurance UK, the goal should be simple.

Find the best price you can.

However, make sure the cover matches reality.

How To Avoid A Car Insurance Mistake Becoming A Bigger Problem

The best time to fix a car insurance mistake is immediately.

Not after a DVLA letter arrives.

Nor after police stop the vehicle.

Not after a claim.

Immediately.

If you spot an error, contact your insurer straight away.

Explain the mistake clearly.

Then ask them to update the policy.

After that, ask for written confirmation.

Keep that confirmation somewhere safe.

Also, check the corrected documents when they arrive.

Because, unfortunately, one correction can sometimes create another mistake.

Here’s the simple rule.

Do not assume.

Check.

Then check again.

This matters even more if you have changed cars, moved house, added a named driver, changed jobs, fitted modifications, or bought a private plate.

Those details can all affect Car Insurance.

They can also affect price.

Therefore, it is much better to correct them before there is a problem.

If your situation has changed, you may also want to compare quotes again.

Sometimes, switching can help.

Sometimes, adjusting your details can change the cost.

Conclusion

The car insurance typo.

One wrong letter should not ruin someone’s life.

However, this case shows how unforgiving car insurance paperwork can become.

The 86-year-old woman believed she had cover.

Yet the system saw something different.

That is the danger.

Car insurance depends on details.

Therefore, every UK driver should check their policy documents carefully.

Check the registration.

The dates.

The address.

Check the named drivers.

Check the parking details.

And, above all, check everything before you relax.

Because Cheap Car Insurance should save you money.

It should not create stress, confusion, or legal trouble.

So, before you chase the cheapest quote, remember this.

Accuracy comes first.

Savings come second.

Peace of mind comes from having both.

For more help, you can read our guides on:

how to save money on car insurance,
telematics car insurance,
comprehensive vs third party cover, and
young driver car insurance tips, especially if you want cheaper cover without accidentally choosing the wrong policy.

Car Insurance Quote

Step 1

Complete your quick and easy quote

Car Insurance

Step 2

Reveal your car insurance policies

Cheapest

Step 3

Pick your favourite and get instant cover